All Categories
Featured

Enhancing Service Spouse Career Success for 2026
Table of Contents
Estimating first-year money flow implies determining possible earnings sources and expenditures and producing a reasonable budget for the preliminary retirement stage, where reduced interim payments are received until the These preliminary payments might be smaller than expected as the Workplace of Personnel Management (OPM) processes the retirement application and payment.
Getting ready for these expenses guarantees that you have enough funds to cover necessary requirements throughout this adjustment duration when you retire. Producing a monetary buffer equivalent to 3-6 months of living expenses supplies a safeguard during the retirement shift. This money reserve assists cover unforeseen costs and makes sure monetary stability while awaiting complete annuity payments to begin when federal staff member retires.
Important files include a marriage certificate, divorce decrees, DD-214 (if appropriate), and updated recipient types. Working with a can assist make sure you've got whatever you need before The retirement application consists of several crucial components, including the SF 3107 type, W-4P form, direct deposit information, and invoices for any deposits or redeposits produced previous service.
New Employment Pathways for Military Spouses
During your last HR evaluation, carefully examine the whole retirement bundle to guarantee all kinds are complete, precise, and constant. Inquire about any agency-specific requirements that might impact your retirement benefits or application processing. Dealing with inconsistencies early can prevent pesky delays. Understand how will be paid out upon retirement. This lump amount payment might have tax ramifications, so consider the timing and prospective influence on your total monetary plan when you leave federal service.
Avoid "burning" sick leave before retiring, as transforming it to additional service credit can considerably improve your retirement payments for life. Review your, considering whether to claim early, at full retirement age, or to delay advantages. Each choice has different implications for your regular monthly payments, affecting the overall federal retirement annuity.
Comprehending how these different incomes incorporate helps you maximize your benefits and protect a solvent future after retirement from your federal job and services. Before submitting your retirement application, carefully verify all benefit elections, consisting of survivor advantages, tax withholding choices, and direct deposit information. Errors in these elections can have long-lasting monetary effects, so accuracy is crucial.
if you are encountering barriers during this time. Consider taking extra actions such as seeking advice from a monetary coordinator, improving your TSP strategy, and enhancing your Social Security claiming choices. These measures ensure your retirement income is maximized and lines up with your long-lasting financial goals after you leave federal services and take a look at your monetary future.
Managing Your VA Claims Options for 2026
Offering assistance on budgeting, saving, and managing costs.
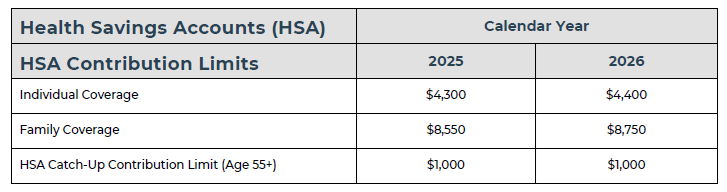
Quick retirement planning note for the federal workers and military servicemen and females out there. Starting in January 2026, you'll be able to do Roth in-plan conversions in your Thrift Cost Savings Strategy (TSP). Simply put, you will now be able to convert cash from your conventional (pre-tax) balance to your Roth (after-tax) balance.
If you have a TSP, I 'd extremely suggest doing some planning deal with your tax and financial consultant to see how it would impact your longer-term tax strategy.
SPB premiums cost up to 6.5% of your pension so that your surviving partner can claim up to 55% of your pensions. Those premiums are non-refundable and can build up with time. Nevertheless, the guaranteed, inflation-adjusted earnings it provides to your partner might be difficult to replicate with private insurance coverage, making it a valuable alternative for lots of households, specifically those without other survivor income sources.
Working with a consultant who comprehends military compensation can help you avoid expensive mistakes.
Mastering the 2026 Military Retirement Transition
In these short, noncredit courses, you'll develop confidence in handling your cash, making a spending plan, preparing for the future, and preparing for retirement. These courses are developed to assist you grow and make smart choices.
Managing Your VA Claims Relief in 2026These noncredit courses are created for personal development, curiosity, and pleasure. Discover how to organize your financial affairs for optimal retirement earnings. In this course, we will talk about property allocation, tax-deferred property management, stock and bond financial investments, Social Security, annuities, and retirement plans such as 401Ks, IRAs, Roth IRAs. Discover and build a plan to provide adequate retirement income for a long life, in addition to strategies to decrease earnings erosion.
Course Start Date End Date Class Arrange Time Trainer Location Credits/CEUs Retirement Planning Today - FI-407 13 Sep 30, 2026 Oct 7, 2026 Wednesday 6:00 AM - 9:00 AM Daniel Hoefferle Northwest - Start Date: Sep 30, 2026 End Date: Oct 7, 2026 Total Charges: $59.00 Learn how to organize your financial affairs for optimal retirement income.

Latest Posts
Overcoming Military Career Gaps

How to Navigate Veteran Benefit Processes
Expert VA Liability Management for 2026